
Managing a company in the UAE is not only about incorporation, banking, and getting a trade license. The real test begins after setup, when deadlines start arriving from different directions: the licensing authority, the Federal Tax Authority, the bank, immigration, landlords, insurers, auditors, shareholders, and sometimes more than one free zone or mainland department.
The risk is not usually negligence. It is fragmentation. One person knows the license expiry date, another has the VAT filing reminder, the bank emails the founder directly for KYC, and the visa renewal sits in a separate portal. By the time someone connects the dots, a deadline has already passed or a renewal is blocked because a supporting document expired first.
A UAE company needs a deadline system, not just a calendar. That system should connect legal, tax, banking, immigration, and governance obligations into one operating rhythm. If you are still in the early post-incorporation stage, Alldren’s guide to managing your business in the UAE after setup is a useful companion to this article. Here, the focus is specifically on how to prevent missed dates once the company is active.
Why UAE company deadlines are easy to miss
The UAE is business-friendly, but it is not administratively light. A company may be simple on paper and still carry multiple recurring obligations. A free zone consultancy with one shareholder, one visa, and no employees may still need to track license renewal, lease or flexi-desk validity, establishment card renewal, visa and Emirates ID dates, Corporate Tax registration, Corporate Tax filing, accounting records, UBO updates, bank KYC, and potential VAT thresholds.
The issue becomes more complex when the business grows. New shareholders, directors, employees, banking relationships, VAT registration, mainland branches, overseas customers, and regulated activities all add extra deadlines or trigger events.
Most missed deadlines come from four common weaknesses:
- The company tracks expiry dates but not preparation dates.
- Obligations sit with individuals rather than a shared company process.
- Tax, banking, licensing, and visa matters are managed separately.
- The business reacts to authority emails instead of running a monthly compliance review.
In practice, a trade license might expire on 30 September, but the renewal work may need to start weeks earlier because the lease, insurance, regulatory approval, audit report, or shareholder resolution must be ready first. The deadline is not the expiry date. The real deadline is the date by which the company must begin preparation.
The five deadline clocks every UAE company should manage
A practical deadline system starts by recognizing that several clocks are running at the same time. Each clock has different owners, portals, documents, and consequences.
1. The licensing and corporate clock
This includes trade license renewal, lease or office agreement renewal, changes to activities, amendments to shareholders or managers, branch renewals, regulatory approvals, and statutory registers. It is the legal shell of the company. If this clock fails, the business may struggle to renew visas, satisfy the bank, sign contracts, or prove good standing.
Free zone and mainland authorities have their own renewal rules, document requirements, and penalties. Some authorities allow online renewal with minimal documents. Others require updated office documents, third-party approvals, or compliance confirmations.
2. The tax and accounting clock
UAE Corporate Tax, VAT, excise tax where applicable, bookkeeping, invoices, tax registration, and return filing all belong here. According to the Federal Tax Authority’s Corporate Tax guidance, UAE Corporate Tax returns and payments are generally due within nine months from the end of the relevant tax period.
VAT has a different rhythm. Businesses that exceed the mandatory VAT registration threshold must register, and VAT returns are typically filed monthly or quarterly depending on the tax period assigned by the FTA. The UAE Government’s VAT overview explains the basic VAT framework, including the standard VAT rate and registration concepts.
A key point for founders: tax deadlines are not only filing dates. They include registration triggers, invoice accuracy, record keeping, reconciliations, and payment readiness.
3. The banking and KYC clock
Banks do not only review a company at account opening. They may request updated trade licenses, shareholder documents, UBO information, contracts, invoices, financial statements, proof of address, tax registration details, or explanations of transactions during periodic KYC reviews.
These requests often come with short response windows. If the company does not reply, banking access may be restricted. A business can be fully licensed and tax-compliant but still face operational disruption because the bank’s compliance team did not receive updated information on time.
4. The immigration and people clock
Visas, Emirates IDs, establishment cards, medical tests, labor approvals, health insurance, payroll requirements, and employee exits all create deadlines. These dates are often connected. A visa renewal may depend on a valid license. An establishment card renewal may depend on authority records being up to date. An employee cancellation may have consequences for payroll, insurance, and final settlement.
Founders often track their own residency date but forget that the company’s immigration file has a separate life cycle.
5. The governance and decision clock
Governance deadlines include board and shareholder approvals, annual confirmations, register updates, UBO updates, nominee director arrangements where used, powers of attorney, signing authorities, and major transaction approvals.
Good governance is not just formality. Banks, investors, tax advisors, auditors, and counterparties often ask for evidence that decisions were properly approved. If resolutions are drafted months after the decision, the company can look disorganized, even if the business itself is sound.
Build a deadline register before building a calendar
A calendar tells you when something is due. A deadline register explains what the obligation is, who owns it, what evidence is required, and what happens if it is not completed.
For managing a company in the UAE, the register should be the central source of truth. It can be a spreadsheet, governance software, or a shared compliance tracker. The tool matters less than the discipline behind it.
A useful register should include at least these fields:
| Field | Why it matters | Example |
|---|---|---|
| Obligation | Defines what must be done | Trade license renewal |
| Authority or counterparty | Shows who controls the deadline | Free zone authority, FTA, bank, immigration department |
| Trigger date | Identifies when the obligation starts | License expiry, VAT threshold crossed, bank KYC email received |
| Internal preparation date | Creates time to collect documents | 45 days before license expiry |
| Final deadline | Records the official due date | Expiry date or FTA filing date |
| Owner | Prevents assumptions | Finance manager, founder, corporate services provider |
| Approver | Confirms who signs or authorizes | Director, shareholder, authorized signatory |
| Evidence | Proves completion | Receipt, renewed license, filed return, confirmation email |
| Escalation rule | Protects against silence | Escalate if not complete 10 business days before deadline |
This format helps prevent a common problem: everyone knows a deadline exists, but no one owns the full chain of actions required to meet it.
Core UAE company deadlines to map
The exact dates depend on your jurisdiction, activity, tax status, employee structure, and authority requirements. Still, most UAE companies should map the following categories.
| Deadline area | Typical trigger | What to track |
|---|---|---|
| Trade license renewal | License expiry date | Renewal requirements, fees, office agreement, approvals, authority portal access |
| Office lease or flexi-desk | Lease or facility expiry | Renewal timing, Ejari where applicable, free zone facility documents |
| Corporate Tax registration | Incorporation date or FTA registration rules | Registration deadline, Tax Registration Number, taxable period, filing date |
| Corporate Tax return and payment | End of financial year or tax period | Return due date, payment due date, supporting accounts, adjustments |
| VAT registration | Mandatory or voluntary threshold trigger | Revenue monitoring, taxable supplies, imports, registration deadline |
| VAT returns and payments | Assigned tax period | Filing date, output VAT, input VAT, reconciliations, payment proof |
| UBO and ownership updates | Change in beneficial ownership or control | Register update, authority notification, supporting documents |
| Manager, director, or signatory changes | Corporate decision or appointment | Resolutions, authority filings, bank updates, powers of attorney |
| Bank KYC | Bank request or periodic review | Updated license, ownership chart, contracts, invoices, financial statements |
| Establishment card and immigration file | Expiry or employee changes | Renewal date, quota status, portal access, linked license validity |
| Visas and Emirates IDs | Individual expiry dates | Medical test, insurance, renewal application, cancellation where needed |
| Accounting close | Monthly or quarterly internal cycle | Bank reconciliation, invoices, expenses, management accounts |
| Insurance and payroll | Policy or payroll cycle | Health insurance, WPS or payroll obligations, employee records |
This table is not a substitute for legal or tax advice. It is a starting map. The company’s final register should reflect the relevant authority rules and the company’s actual activity.
Create an operating rhythm, not a once-a-year scramble
The safest UAE companies do not wait for renewal season. They run a simple operating rhythm that catches issues early.
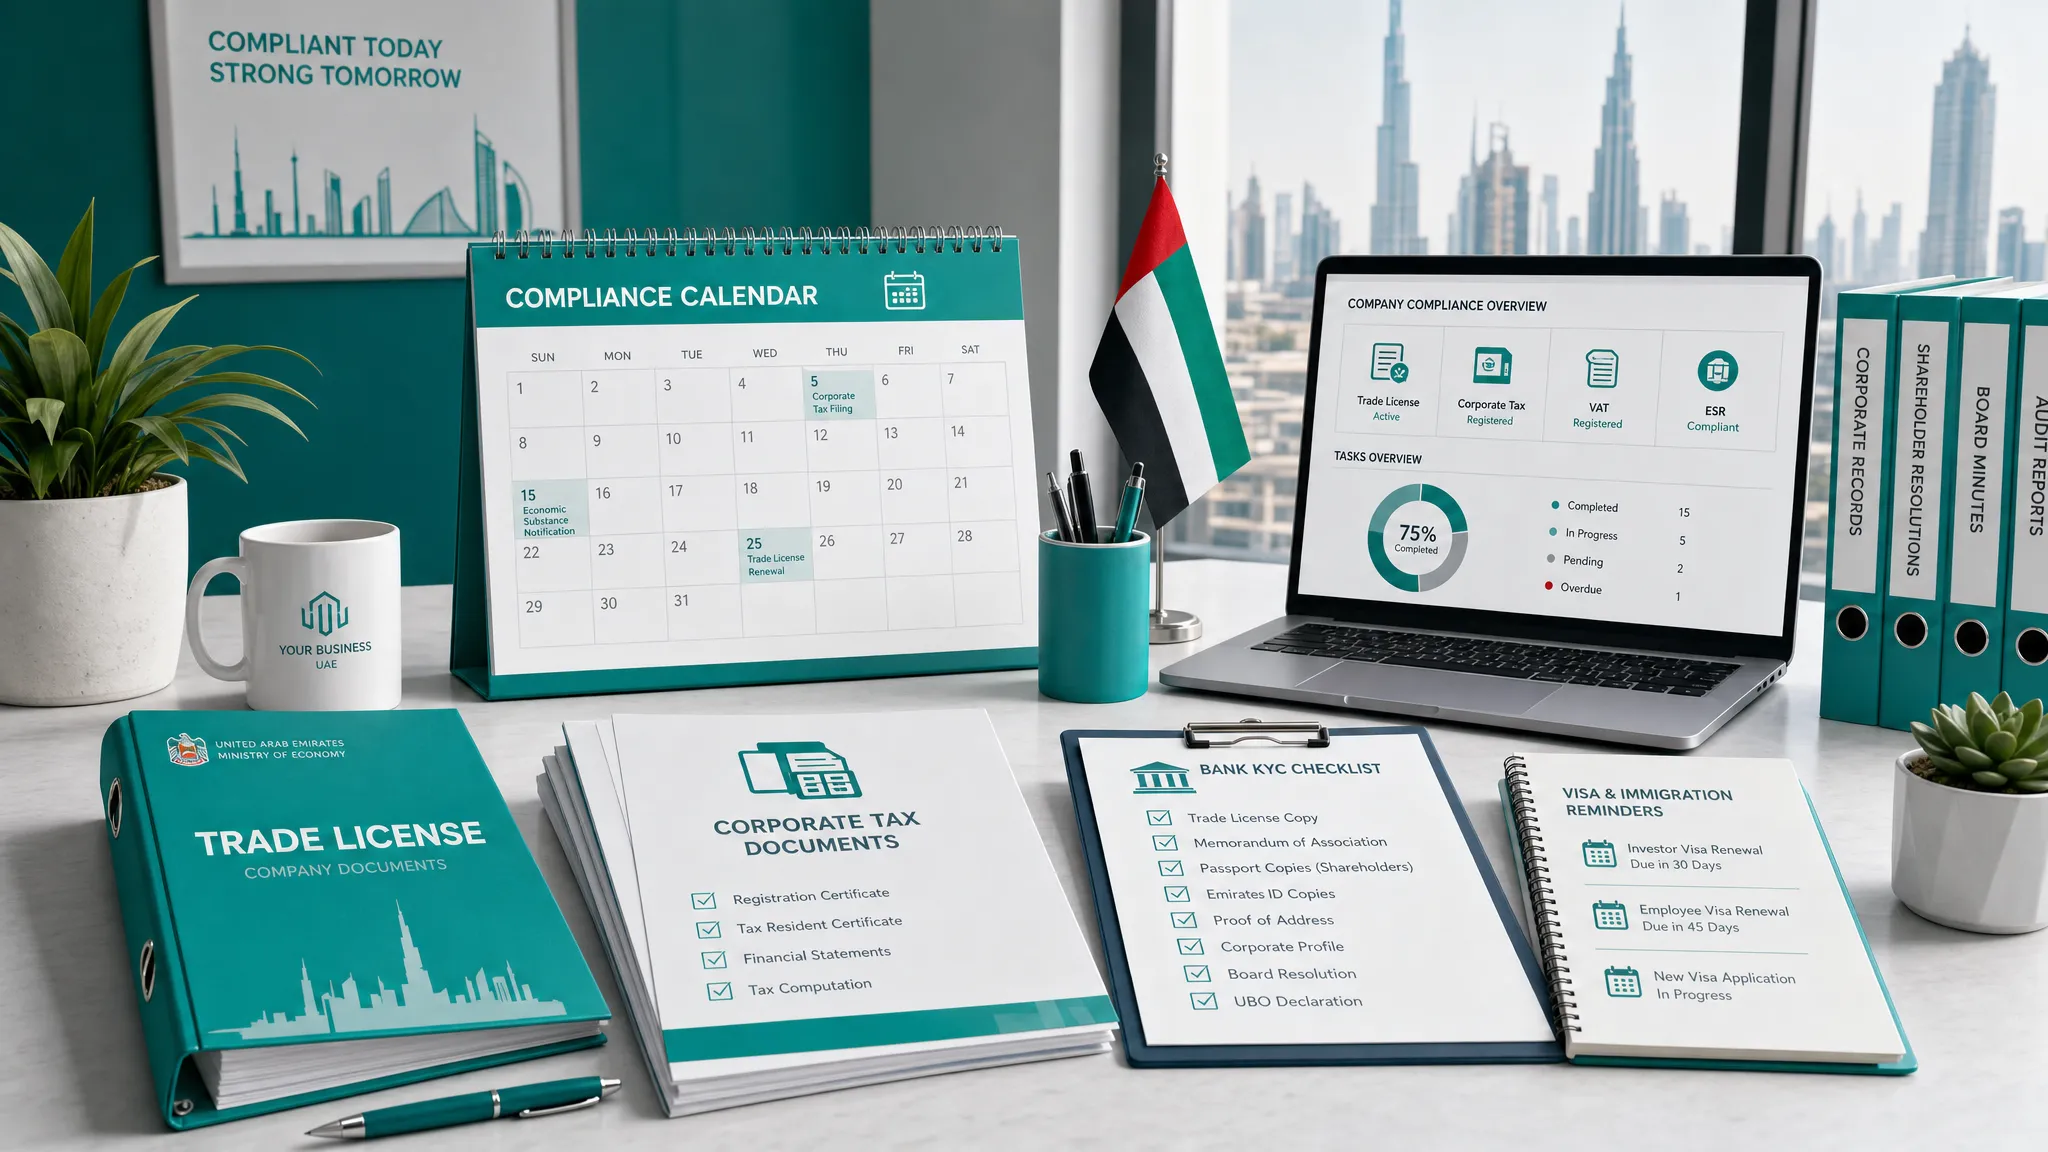
A weekly review can be short. The purpose is to check new authority emails, bank requests, government portal notifications, expiring documents, and any transactions that may trigger tax, VAT, licensing, or governance action. In a small company, this may take 20 minutes. In a larger structure, it may become a formal compliance meeting.
A monthly close is essential. Even if the company is not VAT-registered, bookkeeping should not be postponed until the Corporate Tax return is due. Monthly accounting allows the company to monitor revenue thresholds, prepare tax adjustments, support bank KYC, and understand whether the license activity still matches the actual business model.
A quarterly compliance review should look beyond dates. Ask whether the company’s activity, ownership, management, contracts, invoices, bank transactions, and visas still match the structure on record. Many compliance problems are not missed deadlines at first. They become deadlines later because an unnoticed change requires an authority filing, tax registration, bank update, or license amendment.
An annual pre-renewal review should start well before the trade license expiry date. This is the moment to confirm office needs, visa requirements, ownership records, tax status, bank relationships, powers of attorney, signatory authorities, and governance documents. The best annual renewal is boring because the company has been maintained all year.
Assign ownership before the deadline arrives
Deadlines fail when responsibility is informal. A founder may assume the accountant is watching VAT. The accountant may assume the corporate services provider is watching the trade license. The provider may assume the founder is checking bank emails. Nobody is necessarily wrong, but the system is weak.
Every obligation should have one accountable owner and one backup. The owner does not need to perform every task personally, but they must make sure the task is completed and evidence is stored.
For example, the finance owner may manage bookkeeping, VAT filings, Corporate Tax preparation, and payment confirmations. The corporate owner may manage license renewals, UBO updates, registers, resolutions, and authority filings. The HR or admin owner may manage visas, Emirates IDs, insurance, and payroll documents. The founder or authorized signatory may retain responsibility for approvals, bank communications, and strategic decisions.
Where governance records are involved, use a clear checklist. Alldren’s company secretarial duties checklist sets out the types of corporate records and approvals UAE companies should keep organized.
Store evidence as carefully as you track dates
A deadline is not complete because someone says it is done. It is complete when the company can prove it.
For each obligation, store the final document, submission receipt, payment proof, authority confirmation, email trail, and supporting documents. This matters for tax reviews, bank KYC, audits, investor due diligence, disputes, and future renewals.
A UAE company should maintain an organized document folder for:
- Trade licenses, certificates of incorporation, constitutional documents, amendments, and renewals.
- Shareholder, director, manager, UBO, nominee, and signatory records.
- Board and shareholder resolutions, powers of attorney, and authority approvals.
- Tax registration documents, filed returns, payment proofs, invoices, and accounting records.
- Bank account opening documents, KYC submissions, bank statements, and material correspondence.
- Lease, Ejari where applicable, free zone facility agreements, and office access documents.
- Employee visas, Emirates IDs, labor documents, insurance policies, payroll records, and cancellation documents.
Do not rely only on email inboxes. Employees leave, founders change roles, banks request old documents, and authority portals can be difficult to navigate years later. A structured document repository reduces operational risk.
Watch for trigger events, not only fixed dates
Some UAE deadlines are calendar-based. Others are event-based. Event-based deadlines are easier to miss because they do not appear on an annual renewal calendar.
A change in shareholder, director, manager, UBO, address, office, trade name, activity, bank signatory, or operating model may trigger authority filings, bank updates, tax analysis, or new approvals. Crossing the VAT registration threshold can trigger a registration requirement. Hiring an employee can trigger immigration, insurance, payroll, and labor obligations. Opening a new bank account can trigger new KYC workflows.
A good rule is simple: if the business makes a legal, financial, ownership, people, or operational change, ask whether the deadline register must be updated.
This is especially important for businesses with cross-border directors or shareholders. Decisions made outside the UAE, overseas tax residency, and place of effective management issues can create additional risk. The deadline system should therefore sit inside a wider governance structure, not operate as a purely administrative calendar.
Common warning signs that your deadline system is too weak
If any of the following are happening, the company should tighten its operating process before a deadline is missed:
- Renewals are handled only when an authority reminder arrives.
- The founder is the only person receiving bank KYC emails.
- The accountant sees invoices months after they are issued.
- Corporate records are updated only when the bank asks for them.
- Visa expiry dates are tracked separately from license and establishment card dates.
- The company has no written owner for tax, licensing, banking, governance, and immigration tasks.
- Documents are stored across personal inboxes, WhatsApp chats, and laptop folders.
These are not just admin inconveniences. They can become banking delays, tax penalties, blocked renewals, visa disruption, or due diligence problems.
When external support becomes worth it
Many founders can manage a very simple UAE company internally at first. But external support becomes valuable when the company has multiple shareholders, visas, employees, VAT registration, complex banking, regulated activities, cross-border ownership, nominee arrangements, or frequent corporate changes.
The benefit is not only that someone files documents. The benefit is having a senior-led structure that connects deadlines across licensing, tax, banking, governance, and immigration so that one missed dependency does not create a chain reaction.
If your company is growing beyond a simple founder-managed structure, professional company compliance services can help reduce the time and risk involved in staying current.
Frequently Asked Questions
What is the most important deadline when managing a company in the UAE? There is no single most important deadline. Trade license renewal, Corporate Tax filing, VAT obligations where applicable, bank KYC requests, visa renewals, and UBO updates can all become critical depending on the company. The priority is to manage them in one system rather than separately.
How early should a UAE company start preparing for license renewal? Many companies should begin at least 30 to 60 days before expiry, especially if the renewal depends on office documents, approvals, insurance, shareholder documents, or updated corporate records. The exact timing depends on the authority and business activity.
When is a UAE Corporate Tax return due? Corporate Tax returns and related payments are generally due within nine months after the end of the relevant tax period. Companies should confirm their specific filing obligations, registration status, and tax period with the FTA or a qualified advisor.
Do small UAE companies need a compliance calendar? Yes. Even a small company may have licensing, tax registration, banking KYC, UBO, visa, and accounting obligations. A simple register is often enough, but relying on memory is risky.
What happens if a UAE company misses a deadline? Consequences vary by obligation. A missed deadline may lead to penalties, delayed renewals, bank account restrictions, visa issues, loss of good standing, or additional scrutiny. The impact is usually worse when the company notices the issue late.
Should deadline management be handled by the founder, accountant, or corporate services provider? It depends on the company, but responsibility should be explicit. The founder or board should know who owns each obligation, who approves it, and where completion evidence is stored. In many cases, the best approach is shared ownership with one central register.
Build a UAE company deadline system that does not depend on memory
Managing a company in the UAE becomes much easier when deadlines are treated as part of corporate infrastructure. The goal is not to create bureaucracy. The goal is to make the company bank-ready, tax-ready, renewal-ready, and governance-ready at all times.
Alldren supports UAE companies with expert-led structuring, compliance management, governance, banking support, visas, bookkeeping, tax registration, and ongoing corporate administration. If you want a clearer operating rhythm for your UAE company, start with a structured review of your deadlines, documents, and responsibilities through Alldren.