
Signing limits decide who can move money, how much they can approve and when another director, shareholder or manager must authorize a payment. For a UAE business bank account, those limits are not just online banking settings. They are part of your control framework, bank mandate and corporate governance record.
For founders, finance managers and family offices, the goal is practical: allow routine payments to happen without friction, but prevent one person from having unchecked control over the company’s funds. The right signing limits also make your bank relationship easier to manage because your authority structure matches your business model, licensing and transaction profile.
Why signing limits matter in a UAE bank relationship
UAE banks do not look at a company account as a simple payments tool. They assess who owns the company, who controls it, what activity it carries out and whether its account behavior is consistent with that story. Signing limits sit inside that wider risk picture.
The Central Bank of the UAE sets AML/CFT expectations for licensed financial institutions, and banks apply their own internal risk controls when onboarding and monitoring companies. A clear signing structure helps show that your company has thought through payment authority, not just incorporation paperwork.
There is also an internal risk reason. Without defined approval thresholds, companies often drift into one of two bad patterns: every payment requires owner approval, which slows operations, or one manager has broad authority, which creates fraud, error and succession risks.
If you are still preparing the account application, Alldren’s business bank account opening in the UAE checklist explains the wider document pack banks usually expect before they even get to account operation details.
What counts as a signing limit?
A signing limit is the maximum value, transaction type or banking action a person can approve on behalf of the company. In practice, it usually combines legal authority with bank system permissions.
| Control | What it means | Example |
|---|---|---|
| Authorized signatory | A person recognized by the bank as able to sign or approve for the company | Director, manager, shareholder representative or attorney |
| Monetary limit | A maximum transaction value for one approver or approval group | Single approval up to AED 25,000 |
| Joint signing rule | A requirement for two or more people to approve | Any two directors for payments above a threshold |
| Transaction type limit | Different authority for different payments | Payroll allowed, related-party transfers need extra approval |
| Online banking role | System access for preparing, reviewing or releasing payments | Maker, checker, approver or administrator |
| Daily or monthly cap | Aggregate transfer limit over a time period | AED 100,000 per day for a user group |
The key point is that the online banking portal should implement the governance decision. It should not be the only place where the decision exists. If a dispute arises, the company will need to point back to its board resolution, shareholder approval, power of attorney or bank mandate.
How to set signing limits for a UAE business bank account
Start with the company’s legal authority, not the bank app. The bank will usually ask who is authorized under the company’s constitutional documents, license records, board resolutions or powers of attorney. If those documents are inconsistent, the bank may pause the request or ask for clarifications.
During company setup in the UAE, founders often focus on licensing, visas and the first bank account approval. Signing authority should be decided at the same time because it affects how the bank sees control of the account from day one.
Map who has legal authority
Identify who can bind the company under its documents. This may be the manager named on a trade license, a director, a general manager, a shareholder representative or an attorney appointed under a power of attorney.
For a mainland company, free zone company or holding structure, the exact source of authority can differ. The bank will care less about internal job titles and more about whether the person’s authority is supported by official records.
Match limits to real business activity
A trading company with frequent supplier payments needs a different approval matrix from a consulting company with low monthly overhead. A holding company that occasionally receives dividends or makes investment transfers may need stricter event-based approvals rather than broad daily limits.
Before choosing numbers, map the company’s expected payments: rent, salaries, supplier invoices, tax payments, intercompany transfers, dividends, director fees and foreign exchange transactions. Then set limits that reduce repetitive approvals without allowing sensitive payments to pass without review.
Use a simple approval matrix
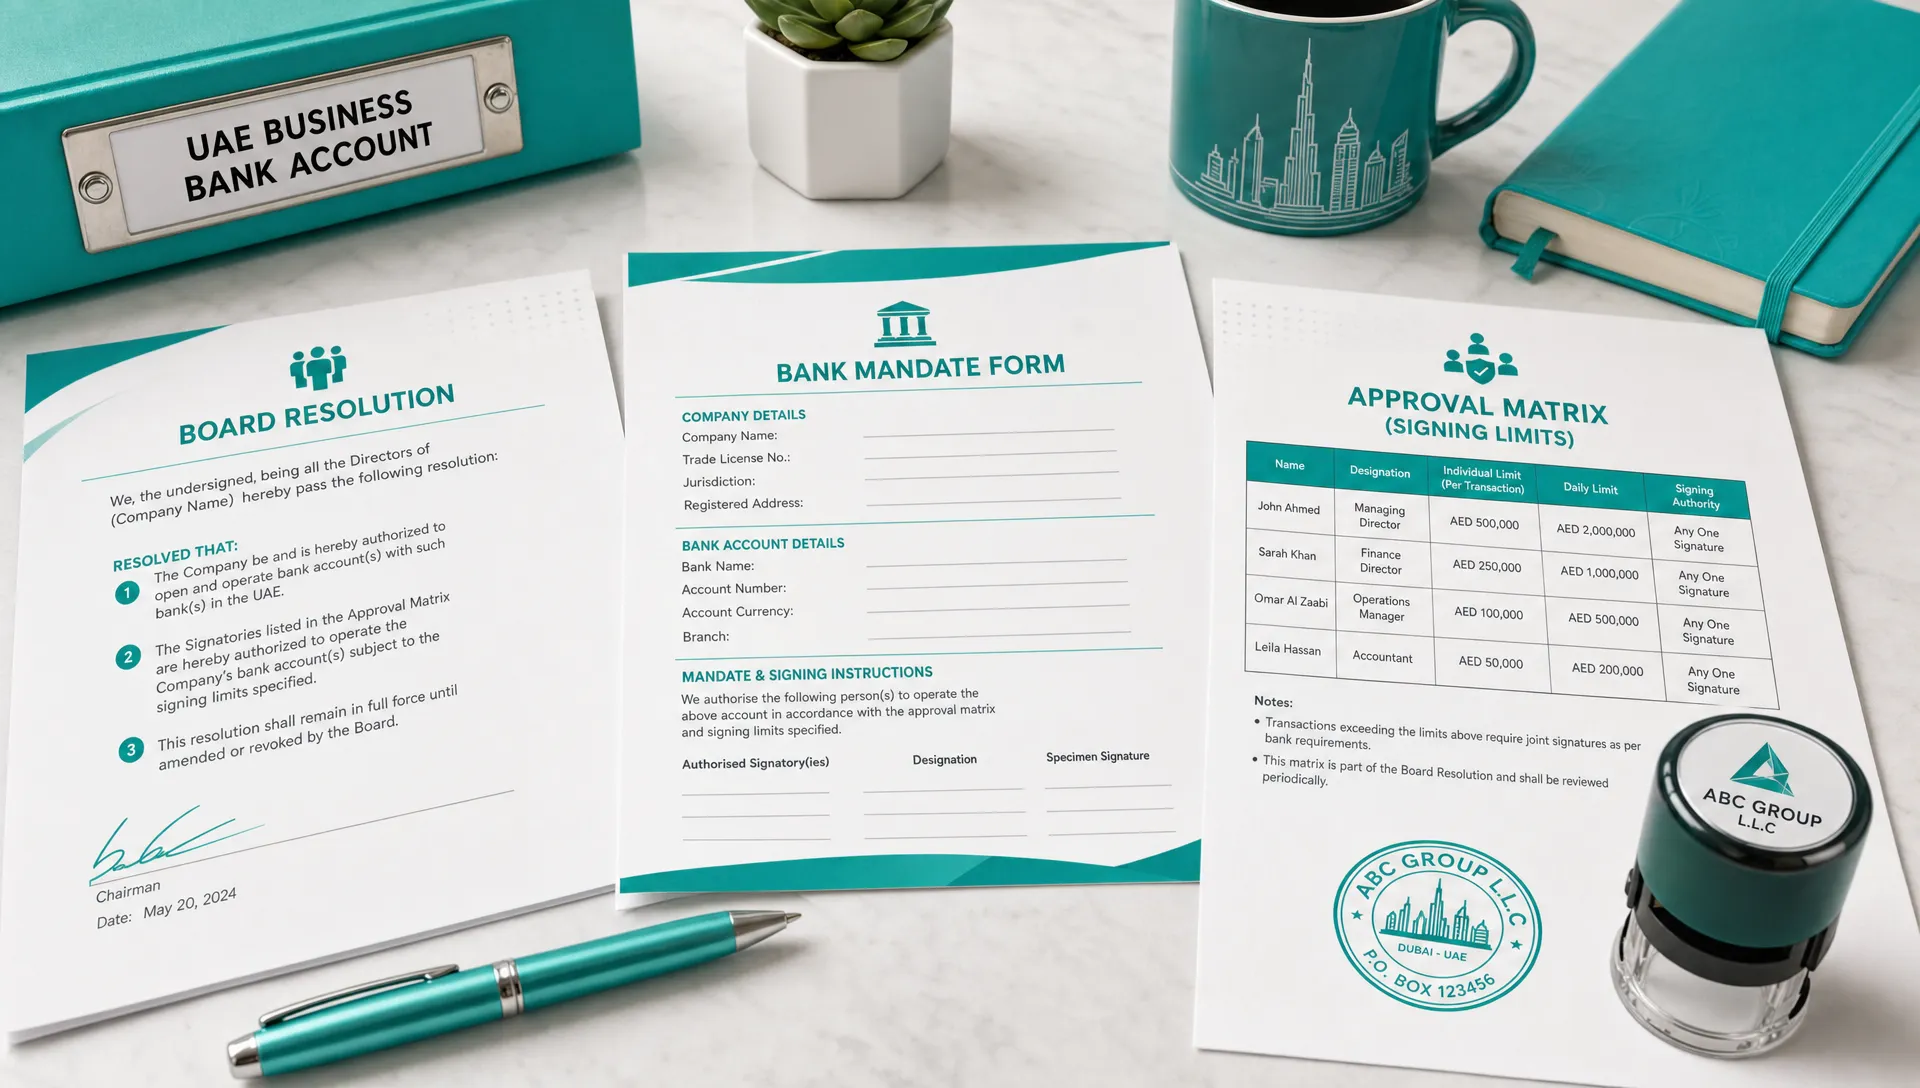
The table below is only an illustrative structure. Replace the amounts and roles with thresholds that reflect your company’s size, risk appetite, bank requirements and internal governance.
| Payment tier | Example threshold | Suggested approval pattern | Typical use |
|---|---|---|---|
| Low value | Up to AED 10,000 | One authorized manager | Utilities, small vendors, subscriptions |
| Operating value | AED 10,001 to AED 75,000 | Finance prepares, manager approves | Regular suppliers, office rent, service providers |
| High value | AED 75,001 to AED 250,000 | Two authorized signatories | Major supplier invoices, asset purchases |
| Exceptional value | Above AED 250,000 | Board or shareholder approval plus bank signatories | Capital movements, loans, acquisitions, unusual transfers |
| Sensitive payments | Any amount | Second approval required | Related-party transfers, new overseas beneficiaries, dividends |
This type of matrix gives the bank and your internal team a shared reference point. It also helps avoid overloading directors with small payments while protecting large or unusual transfers.
Separate makers, approvers and administrators
Many companies make the mistake of focusing only on who can approve a transfer. Online banking roles matter just as much.
A maker prepares payments but does not release funds. A checker reviews details, supporting documents and beneficiary information. An approver releases the payment within the authority granted. An administrator may be able to add users, reset access or change permissions, so that role needs tight control.
For a small company, one person may prepare payments and another may approve. For a larger company, the finance team can prepare batches, the finance manager can review them and directors can approve payments above defined thresholds.
Beneficiary creation deserves special attention. Fraud often occurs when payment details are changed rather than when a payment is approved. Consider requiring second approval for new beneficiaries, overseas beneficiaries and changes to existing supplier bank details.
Document the limits before the bank implements them
Banks usually work from formal documents, not informal emails. Your internal decision should be reflected in a clean board resolution, shareholder resolution, bank mandate or power of attorney, depending on the company type and bank’s process.
A practical documentation process looks like this:
- Review the company’s memorandum, articles, license and existing mandates.
- Confirm who has legal authority to appoint or remove bank signatories.
- Approve the signing matrix through the correct corporate body.
- Complete the bank’s mandate forms using the same names, passport details and roles.
- Configure online banking permissions so they mirror the approved mandate.
- Keep signed resolutions, bank confirmations and online banking access records in the company file.
If your bank account is still being opened, align this work with the KYC file. Banks will be comparing your license activity, ownership, signatories and projected transactions. Alldren’s guide on what banks want to see from new UAE businesses is a useful reference for building that consistent account narrative.
Special points for UAE company structures
Signing limits should reflect the structure you actually operate, not a generic template. This is especially important where the UAE company is part of an international group, a family holding structure or a free zone setup with foreign shareholders.
Free zone and Ras Al Khaimah structures
For Ras Al Khaimah company formation, the same principle applies whether the company is a RAKEZ free zone operating business or another licensed entity: the person signing should be traceable to the company records and mandate.
If a company has corporate shareholders, the bank may ask to see the authority chain from the parent company down to the UAE signatory. A signing limit matrix will not fix missing corporate approvals, but it can make the operating model clearer once the authority chain is documented.
RAK ICC offshore and holding companies
A RAK ICC offshore structure or another offshore company in the UAE may have limited day-to-day operating expenses but larger strategic transactions. In that context, low routine limits and stricter approvals for investments, loans, dividend flows and related-party transfers often make more sense than giving one signatory broad payment authority.
Banks may scrutinize offshore and holding structures more closely because activity can be less visible than in an operating company with local invoices, payroll and premises. Your signing limits should support the stated purpose of the entity.
Groups, family businesses and nominee directors
Groups often want headquarters finance teams to control payments across subsidiaries. That can work, but the authority must be properly delegated and accepted by the relevant bank. Family businesses should also decide whether next-generation family members have viewing access, preparation access or approval authority.
If a nominee director is part of the structure, avoid relying on informal side instructions. Authority, limits and escalation rules should be recorded carefully so that the bank mandate, corporate governance file and practical operation of the account all point in the same direction.
Common mistakes to avoid
The most common signing limit problems are usually simple and preventable. They tend to appear when the business grows but the bank mandate remains unchanged.
- Giving one person unlimited signing power because it was convenient during setup.
- Setting online banking limits that conflict with the board resolution or power of attorney.
- Allowing the same person to add beneficiaries, prepare payments and approve transfers.
- Forgetting to include cards, cheques, foreign exchange deals and standing instructions in the control framework.
- Leaving former employees or former directors with active banking access.
- Using a personal account for business inflows instead of fixing the company account structure.
That last point is becoming harder to ignore. If a company cannot operate smoothly because its signing rules are badly designed, some founders are tempted to route payments through personal accounts. Alldren explains why that approach creates serious risk in its article on using personal bank accounts for business in the UAE.
When should signing limits be reviewed?
Review signing limits whenever the company changes in a way that affects control, risk or transaction volume. At minimum, many companies review them annually alongside corporate renewals, compliance checks and bookkeeping reviews.
You should also review limits when a shareholder changes, a director resigns, a finance employee leaves, the company opens a new branch, monthly transaction volume increases, a new bank account is added or the business starts making larger international payments.
The tax and accounting angle matters too. VAT payments, corporate tax obligations, bookkeeping controls and audit trails all benefit from clear approval evidence. If your UAE tax advisory team or bookkeeper cannot tell who approved a payment and why, the signing framework is not doing its job.
Sample wording for a UAE bank mandate or board resolution
The exact wording should be adapted to your company documents, bank forms and legal advice. Still, the structure below shows the level of clarity you should aim for.
Resolved that [Name], holder of passport number [number], in the capacity of [role], is authorized to operate the company’s bank account with [bank name] and approve transactions up to AED [amount] per transaction.
Resolved that transactions above AED [amount] require approval by any two of the following authorized signatories: [Name 1], [Name 2] and [Name 3].
Resolved that the creation of new beneficiaries, amendment of beneficiary bank details, related-party transfers and transfers above AED [amount] require dual approval regardless of transaction value.
Resolved that online banking user roles shall be configured to reflect the signing authority approved in this resolution, including maker, checker, approver and administrator permissions.
This wording is not a substitute for legal drafting. It simply shows how to connect transaction value, user role and sensitive payment type in one governance record.
Frequently Asked Questions
Can a UAE company have more than one authorized signatory? Yes. Many UAE companies appoint multiple authorized signatories and define whether they can act alone, jointly or only within specific transaction limits. The bank will need supporting corporate documents and completed mandate forms.
Do banks set signing limits or does the company choose them? The company proposes its signing authority through resolutions and mandate forms, but the bank decides what it will accept and how it will configure account access. The bank may also apply its own risk controls and transaction limits.
Should small UAE companies use dual approval? Often, yes, at least for higher value transfers, new beneficiaries and sensitive payments. A very small company may keep routine payments simple while still requiring a second approval for unusual or high-risk transactions.
Can signing limits be changed after the account is opened? Yes, but the bank will usually require updated resolutions, revised mandate forms and identity documents for any new signatories. The online banking settings should be updated only after the corporate approval is properly documented.
Are signing limits needed for a free zone or offshore company? Yes. Free zone and offshore companies still need a clear bank mandate. For holding or offshore structures, signing limits are especially useful because transactions may be less frequent but higher in value.
Build signing authority into the structure from the start
Signing limits are easiest to get right before the account is active, not after a payment dispute, blocked transfer or staff departure. Treat them as part of company setup, compliance and governance, not as an afterthought inside an online banking portal.
Alldren supports UAE company structuring, bank account opening coordination, ongoing compliance, governance records, bookkeeping and tax registration. If you want a bankable structure with clear authority from the beginning, speak with Alldren before your next mandate is submitted or updated.